Auction or Private Sale: What Does the Price Really Tell Us?
Disndat
An examination of auction buyer premiums, private sale commissions, enhanced-hammer agreements, irrevocable bids and the economics of selling valuable objects.
001
The auction room produces a public record of value. The private market offers discretion, flexibility and the possibility of a better deal. Yet behind both methods lies a network of negotiations that rarely becomes visible to the people trying to understand what an object is worth.
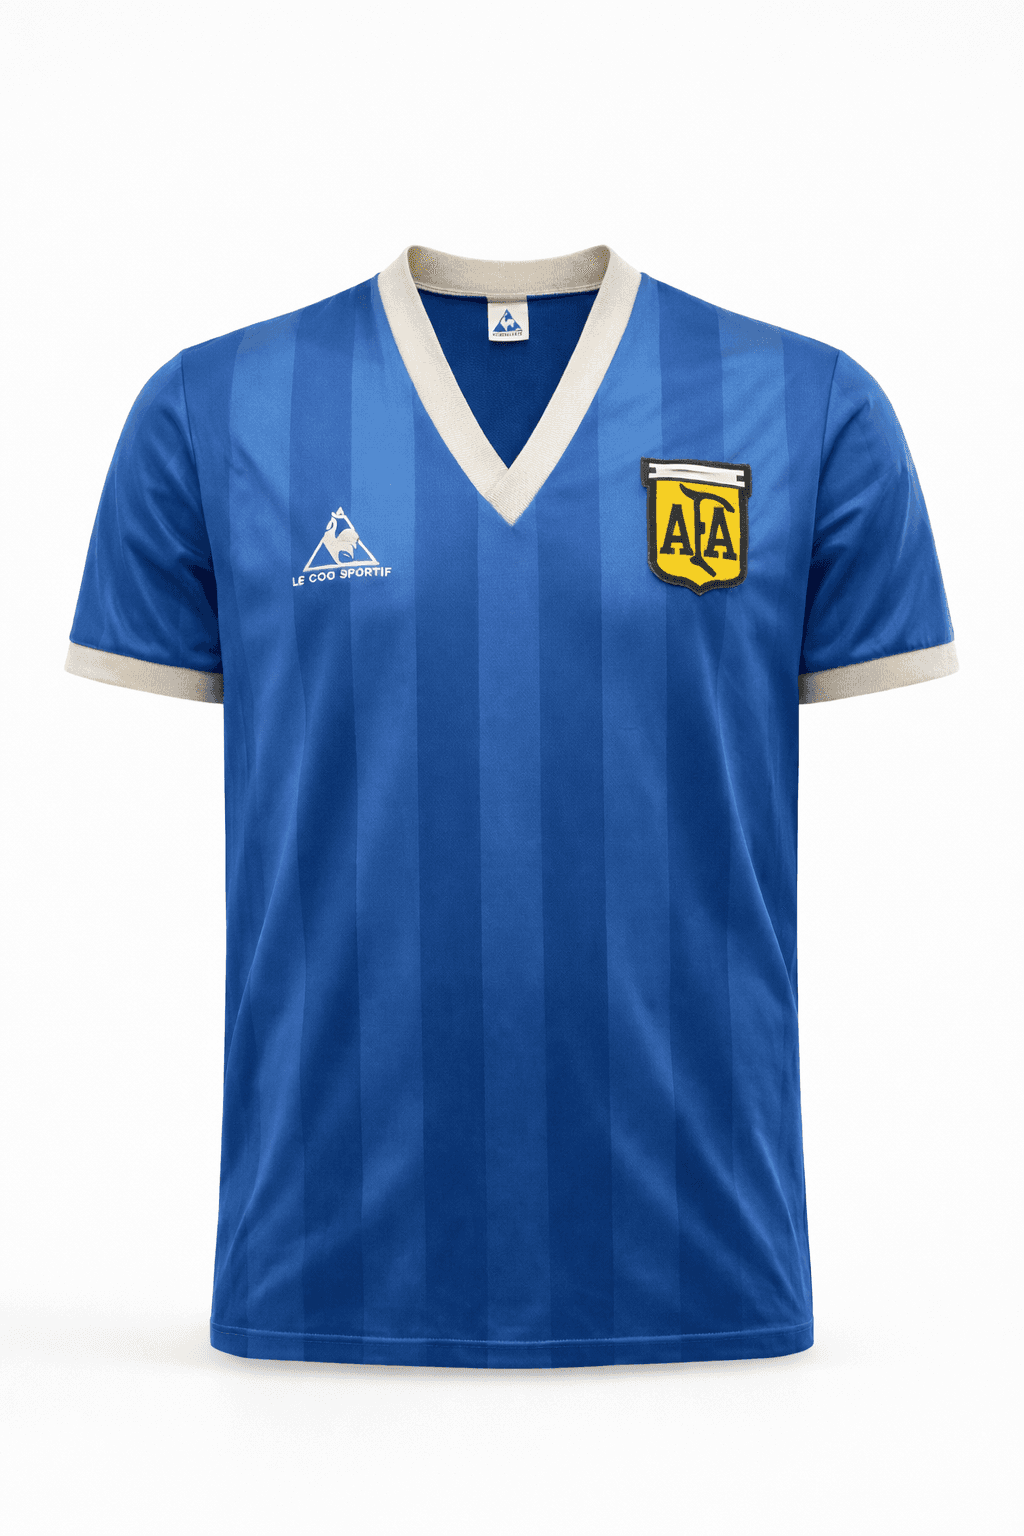
Diego Maradona's shirt from Argentina's 1986 World Cup quarter-final against England, offered at Sotheby's in May 2022.
On the afternoon of 4 May 2022, with nine minutes remaining in a two-week online auction, Diego Maradona's famous blue Argentina shirt had attracted a single bid of £4 million.
It was the shirt worn during the 1986 World Cup quarter-final against England, when Maradona scored both the notorious Hand of God goal and what would later be celebrated as the Goal of the Century. Former England midfielder Steve Hodge had exchanged shirts with Maradona after the match and kept it for more than three decades.
Sotheby's estimated the shirt at between £4 million and £6 million. For almost the entire auction, there was little visible competition.
Then, in the final minutes, another bidder entered at £4.2 million. Further bids followed. By the time the auction closed, the shirt had sold for £7,142,500, including the auction premium.
The result was a record for sports memorabilia at the time. It was reported around the world, entering the permanent history of an object that already occupied an extraordinary place in football culture.
But one detail of the sale received considerably less attention.
Sotheby's catalogue identified the shirt as subject to an irrevocable bid: a financial arrangement under which a bidder commits to purchasing an object at an agreed level before the auction concludes. In certain circumstances, these arrangements can provide the committed bidder with financial compensation if another person ultimately wins.
The auction publicly established what the successful buyer paid. It did not disclose the commercial arrangements between the auction house, the seller and the party providing that commitment.
That distinction provides a useful starting point for understanding how valuable objects are sold.
The conventional choice is between an auction and a private sale. One is assumed to offer public competition, the other a discreet negotiation. Auction prices become reference points for an entire market; private-sale prices may never be known outside the transaction.
Both descriptions are broadly correct. Neither captures the complete economics.
An auction can be public in its bidding and private in its financial arrangements. A private sale can be confidential in its negotiation and deliberately public in its result.
The relevant question is therefore not simply which method produces the highest price.
It is who benefits from the transaction, what information each participant receives, and how much of the object's eventual value is retained by the people facilitating its sale.
The price of an auction
At its simplest, an auction is a mechanism for price discovery.
An object is catalogued, researched and presented to potential buyers. An estimate provides an indication of expected bidding, while a reserve establishes the minimum price at which the seller has agreed it may be sold. Bidders compete, and the highest qualifying bid determines the hammer price.
For a seller, the appeal is the prospect of competition. A determined buyer may discover that another person values the object more highly than anticipated. For a buyer, the process provides a defined opportunity to acquire something that may rarely appear on the market.
The auction house provides the infrastructure between them.
Specialists undertake research, assess condition and provenance, prepare catalogues and introduce objects to collectors. The institution manages marketing, exhibitions, bidding, administration, payment and the contractual machinery surrounding a transaction.
Those services can be expensive to provide.
The Art Basel and UBS Art Market Report 2026, prepared by Arts Economics, found that average operating costs among mid-tier auction houses rose by 5 per cent in 2025. Forty per cent of the houses surveyed reported lower annual profits.
The buyer's premium is an important source of the revenue needed to sustain that business. It is charged in addition to the hammer price and is usually calculated according to a published schedule.
As of September 2026, both Sotheby's and Christie's charge a standard buyer's premium of 28 per cent on the first £1.5 million of hammer price at their London auctions. The marginal rate falls to 22 per cent on the portion between £1.5 million and £6 million, and to 15 per cent above £6 million. Certain categories have different schedules.
The amount is substantial, but its existence is not concealed. A prospective buyer can inspect the applicable rate before placing a bid.
What is much less apparent is how the money is distributed after a sale.
What a £100,000 hammer price actually produces
Consider an object sold at auction for £100,000.
Under the standard 28 per cent buyer's-premium rate, the successful buyer owes £128,000 before applicable taxes or additional charges.
Suppose the seller has agreed to pay the auction house a commission of 10 per cent of the hammer price. Sotheby's currently publishes 10 per cent as its standard seller's commission, although negotiated terms can differ.
The financial outcome would look like this:
Transaction | Amount |
|---|---|
Hammer price | £100,000 |
Buyer's premium, 28% | £28,000 |
Buyer expenditure | £128,000 |
Seller's commission, 10% | £10,000 |
Seller proceeds | £90,000 |
Auction house's gross retention | £38,000 |
Illustrative transaction using published standard fees. VAT, other seller charges, financing arrangements and any additional success fees are excluded.
The buyer spends £128,000. The seller receives £90,000.
The £38,000 difference represents gross commission income associated with the sale. It does not represent the auction house's profit: staff, premises, marketing, financing, insurance, administration and other operating costs still have to be accounted for.
Nor does this example describe every Sotheby's consignment. Its published terms also include a success fee in certain circumstances when a lot exceeds its high estimate, and commercially important consignments may be negotiated individually.
Nevertheless, the difference between buyer expenditure and seller proceeds deserves considerably more attention than it usually receives.
Public reporting tends to concentrate on the amount paid for an object. Sellers are understandably more interested in what they receive.
The two numbers are not interchangeable.
The auction before the auction
Long before the first public bid, another competition may already have taken place.
Auction houses compete for the right to sell important objects. An exceptional collection, a historically significant artwork or an unusually desirable piece of memorabilia can attract proposals from several institutions.
In the experience of a Disndat founder during his earlier work at Sotheby's, commercial terms could be negotiated on individual lots or entire collections. When rival auction houses were pursuing the same consignment, the terms offered to a seller could become significantly more favourable.
This was not simply a question of whether the seller paid the standard commission.
An auction house might waive that commission altogether, allowing the seller to receive 100 per cent of the hammer price. In particularly competitive circumstances, it could offer more than the hammer price itself.
The additional amount would effectively come from the buyer's premium.
The practice is commonly described as an enhanced hammer. Its existence is independently documented in securities filings by art-investment businesses, which explain that auction houses may waive seller commissions and rebate part of the buyer's premium to secure high-value consignments.
Using the same hypothetical £100,000 hammer price and a 28 per cent buyer's premium, the economics change considerably:
Negotiated seller payout | Seller receives | House retains, before costs |
|---|---|---|
90% of hammer | £90,000 | £38,000 |
100% of hammer | £100,000 | £28,000 |
105% of hammer | £105,000 | £23,000 |
110% of hammer | £110,000 | £18,000 |
Illustrative contractual arrangements, not disclosed terms from an actual consignment. The figures exclude taxes, additional charges and any payments to third parties.
In every scenario, the winning buyer pays the same £128,000.
Yet the difference between the least and most favourable seller arrangements is £20,000.
The auction house may be prepared to surrender a significant proportion of its potential revenue because winning the consignment has value beyond the commission earned on that single object.
An exceptional lot can attract important collectors, encourage additional consignments, strengthen a department's reputation and create publicity for an entire sale. A significant collection may represent months of specialist work and a commercial opportunity that extends well beyond its individual lots.
There is consequently a market for the consignment before there is a market for the object.
The strongest sellers may be able to negotiate favourable terms precisely because several institutions want their business.
This introduces an important qualification to the assumption that auctions are inherently expensive for sellers.
An auction may charge buyers a substantial premium while offering an exceptional consignor a remarkably competitive net return.
The published fee schedule tells us what the buyer is charged. It does not necessarily tell us what the institution ultimately earns.
The people who get paid not to win
A second negotiation can take place on the buying side.
Auction houses sometimes provide sellers with guarantees: contractual assurances that an object will produce at least an agreed amount, regardless of the outcome of public bidding.
A guarantee offers certainty to the seller, but it can transfer financial risk to the auction house.
If the object fails to sell or achieves less than the guaranteed amount, the institution may have to make up the difference or acquire the object itself.
To reduce that exposure, an auction house can involve a third party willing to underwrite some of the risk.
This is where irrevocable bids become significant.
An irrevocable bidder commits to purchasing the object at an agreed level if no higher bidder emerges. The commitment may help the institution secure the consignment and provide an assured starting point for the sale.
But the irrevocable bidder does not necessarily participate on the same economic terms as every other buyer.
In return for accepting the risk of having to complete the purchase, the bidder may receive compensation.
Historical financial filings from Sotheby's, when it was a publicly listed company, describe arrangements under which unsuccessful irrevocable bidders could receive a share of the auction commission, a share of the amount achieved above the guaranteed level, or both.
Christie's current published guidance also explains that remuneration for an unsuccessful third-party guarantor may be a fixed fee or an amount calculated by reference to the final hammer price.
The precise arrangement depends on the transaction.
Consider a hypothetical object with an irrevocable commitment of £4 million.
Suppose bidding eventually takes the hammer price to £6 million. If the committed bidder had negotiated a payment equal to 10 per cent of the £2 million increase, that party would receive £200,000 without acquiring the object.
This is only an illustration of one possible compensation structure. It is not evidence that every irrevocable bidder receives such a percentage.
The principle is nonetheless remarkable.
An individual can participate in an auction, lose the object and still earn money from the sale.
That financial return is compensation for taking on a genuine commitment. If competitive bidding fails to materialise, the irrevocable bidder may be obliged to buy the object, potentially at a price above what other buyers are prepared to offer.
This is not risk-free speculation.
The arrangement nevertheless creates a different kind of participant: somebody who may be interested both in owning the object and in the financial consequences of being outbid.
The Maradona shirt
The 2022 Maradona auction provides an unusually visible example of how this mechanism can sit behind a public sale.
The original Sotheby's catalogue identifies the lot as subject to irrevocable bids. Contemporary reporting records a £4 million bid standing for much of the auction, followed by late competition that took the final buyer-inclusive price to £7,142,500.
These are established facts.
What is not publicly established is the identity of the irrevocable bidder, the precise contractual level of the commitment or the amount, if any, that the bidder ultimately received.
The opening £4 million bid and the published final price should not be used to calculate a hypothetical bidder's actual earnings. The final result included the buyer's premium and therefore was not directly comparable with the earlier bid.
The public record allows us to establish that an irrevocable-bid arrangement existed. It does not reveal the arrangement's economics.
That is precisely why the example is interesting.
The final price was reported around the world. It remains a reference point for the market in historic sporting objects.
Yet the distribution of money between the seller, auction house and any party underwriting the sale is not available for an outside observer to reconstruct.
The price was public. The financial architecture surrounding it was substantially private.
How transparent is a public auction?
Auction houses provide an important form of transparency.
Published estimates, conditions of sale, premiums, catalogue descriptions and results allow buyers to make informed decisions and give subsequent researchers an observable record of market activity.
Irrevocable bids and financial interests are also subject to disclosure requirements under auction-house conditions. Relevant lots can be identified in catalogues or through sale notices.
These disclosures matter, and it would be misleading to suggest that the arrangements are uniformly concealed.
But there is a difference between knowing that a financial interest exists and knowing its value.
A bidder may be informed that an irrevocable bid has been placed without learning the precise compensation offered to the party providing it.
A seller knows the terms of their own agreement but may not know every element of the auction house's separate financial arrangements.
A buyer can calculate the premium they are being charged without knowing whether the seller is receiving 90, 100 or 110 per cent of hammer.
An outside observer usually has even less information.
It is therefore useful to distinguish three kinds of transparency.
The transparency of the process: how an object is offered, how bids are accepted and what contractual rules govern the sale.
The transparency of the price: what the final buyer was required to pay and, where reported, the hammer price that produced it.
The transparency of the economics: how the money was divided among the parties who facilitated, guaranteed or participated in the transaction.
Public auctions can perform well on the first two measures while remaining considerably less transparent on the third.
There is also a smaller distortion in the historical record.
Auction results are commonly reported inclusive of buyer's premium. That premium changes over time.
If an object sells for a £100,000 hammer price with a 26 per cent premium, the published result is £126,000. At a 28 per cent premium, the same hammer price produces a reported result of £128,000.
The apparent sale price increases by approximately 1.6 per cent without any change in the hammer bid.
In reality, changing fees may influence bidding behaviour, so this calculation cannot predict what buyers would actually offer.
It does, however, show why historical auction results need to be compared carefully. An increase in the published figure does not always correspond to an equivalent increase in the amount bid for the object itself.
The private market
Private sales operate without the same public calendar or requirement for competitive bidding.
An owner may approach an auction house's private-sales department, a specialist dealer, a gallery or an independent intermediary.
Rather than presenting the object to a public audience, the intermediary identifies buyers who may have a particular interest in acquiring it.
The price is negotiated. So are the timing, payment arrangements, confidentiality and other contractual conditions.
Sotheby's describes its private-sales service as operating throughout the year, offering sellers greater control over exposure and price through an individually agreed fee.
For some objects, this flexibility is more valuable than the possibility of an auction result.
An owner may wish to avoid publicising financial circumstances or signalling that an asset is available. A buyer may prefer to remain anonymous. An object may have a small, specialist audience that can be approached directly without the cost of a major auction campaign.
Private sales also allow an owner to test the market without making every unsuccessful negotiation publicly visible.
But the absence of a public record creates a different informational problem.
An asking price is not necessarily an achieved price. A dealer's opinion of value is not necessarily supported by a completed transaction. And a figure communicated by an intermediary may include an undisclosed trading margin.
The distinction between a dealer and an agent becomes especially important.
An agent generally acts on behalf of a principal under an agreed mandate. A dealer acting as principal may instead purchase an object and resell it at a higher price, earning the difference.
The legal obligations and disclosure requirements depend on the actual relationship and jurisdiction. Neither arrangement is inherently improper.
The difficulty arises when the buyer or seller does not clearly understand which arrangement applies.
In a private market with limited publicly available price information, a knowledgeable intermediary can possess a substantial informational advantage.
That advantage may be entirely legitimate. It can reflect years of research, an established network of collectors and an ability to identify demand that would otherwise remain inaccessible.
But it can also be difficult for the other parties to evaluate.
A $44.5 million difference
In 2013, the Swiss art dealer Yves Bouvier acquired Salvator Mundi, attributed to Leonardo da Vinci, through Sotheby's for approximately $83 million.
He subsequently sold the painting to the Russian collector Dmitry Rybolovlev for $127.5 million.
The difference between the two prices was $44.5 million.
That was a difference between successive transaction prices, not necessarily Bouvier's final profit after costs and other obligations.
The transactions later became central to a lengthy legal dispute over the relationship between the dealer and collector.
Rybolovlev alleged that Bouvier had been acting as an agent while charging undisclosed markups. Bouvier denied wrongdoing and maintained that he was acting as an independent dealer entitled to negotiate his own prices.
The two men settled their legal disputes in December 2023. In January 2024, a New York jury found in favour of Sotheby's, rejecting Rybolovlev's claims that the auction house had assisted the alleged fraud. Bouvier was not a defendant in that trial.
The case should not be interpreted as proof of wrongdoing by Sotheby's or of widespread dishonesty among private dealers.
It does, however, demonstrate the commercial importance of understanding an intermediary's role.
For the buyer, the distinction between a negotiated agency fee and a principal's resale margin can involve extraordinary sums.
A private transaction may provide discretion and efficiency, but those advantages do not remove the need to establish who represents whom, whether the intermediary owns the property, and how their remuneration is determined.
The apparent simplicity of an agreed purchase price can conceal a surprisingly complicated chain of financial interests.
When a private sale becomes public
Not every private transaction remains confidential.
In April 2021, Sotheby's announced that the Nike Air Yeezy 1 prototypes worn by Kanye West during his 2008 Grammy Awards performance had sold privately for $1.8 million.
The buyer was identified as RARES, a platform then offering fractional ownership of collectible sneakers.
It was a remarkable figure for an object from a market that had only recently gained dedicated attention within major auction houses.
The sale attracted considerable publicity. Its price became an important reference point in the developing market for historically significant sneakers.
Yet the transaction itself had not been conducted through a public auction.
The price was made public because disclosure served a purpose.
For the auction house, the result demonstrated its ability to handle valuable objects outside traditional collecting categories. For the buyer, it brought attention to a high-profile acquisition. For the wider market, it created a reference around which subsequent valuations and conversations could develop.
The private sale had produced something that usually makes auctions distinctive: a publicly recognised price.
But the price did not reveal the underlying negotiation or establish whether other buyers would have paid more.
This is an important reminder that publicity and price discovery are not the same thing.
A private-sale price can be announced to the world without having been tested through public competition.
Equally, a public auction can produce a celebrated result even when part of its financial risk was committed before the bidding began.
Why the public record matters
According to the Art Basel and UBS Art Market Report 2026, worldwide public auction sales reached approximately $20.7 billion in 2025, an increase of 9 per cent.
Private sales conducted through auction houses amounted to just under $4.2 billion, down approximately 5 per cent.
These figures do not describe the whole private market. The substantially larger dealer and gallery sector operates through transactions that are often reported in aggregate without disclosing individual prices.
This is one of the central differences between the two markets.
Public auctions produce a body of comparable evidence that can be used by collectors, specialists, insurers, researchers and future sellers.
Private sales can produce equally significant transactions without contributing comparable information to the public record.
The auction result therefore has a value beyond the people directly involved.
An object sells once, but its price may be cited for years.
For categories in which large numbers of comparable objects are traded, an individual result can be evaluated against a wider range of evidence.
For unusual prototypes, film-used objects, historically significant footwear or other emerging collectible categories, one sale may carry disproportionate influence.
That can be useful, but it can also be misleading.
A record price may reflect exceptional provenance, an unusually committed buyer, a particular promotional campaign or a moment of intense attention. It does not necessarily establish a new valuation for every superficially similar object.
The public auction provides evidence of a transaction. It does not establish a permanent or universal value.
Nevertheless, the record exists.
And that is something the private market frequently does not provide.
In this sense, the auction house is not simply selling objects. It is producing information that becomes part of the infrastructure of the collecting market.
The buyer and seller pay for the transaction, but its reported outcome may benefit people who never participated.
Which method actually makes sense?
For an owner, the decision should begin with a realistic assessment of demand.
How many credible buyers exist for the object? Can they be identified directly? Would bringing them into competition produce a materially better result? Is the seller prepared to accept the risk of an unsold lot?
Auction is particularly attractive when an object has broad recognition, strong documentation and several potentially competing buyers.
An institution may provide confidence through cataloguing and specialist research, and its international audience may reveal demand that a private intermediary would struggle to reach independently.
But the seller must assess the actual contractual terms rather than rely on the institution's reputation.
The reserve, estimated price range, seller's commission, enhanced-hammer arrangements, any guarantee, additional expenses and likely settlement timetable all affect the result.
A published auction estimate is not a promise of what the seller will receive.
Private sales can be more effective when the audience is smaller but clearly identifiable, when discretion has substantial value, or when a strong net price is available without exposing the object to public bidding.
The owner retains flexibility over negotiation and can sometimes avoid the reputational consequences of an unsuccessful public sale.
The question of commission is particularly important.
Return to the hypothetical object that achieves a £100,000 hammer price at auction.
If its seller has negotiated 110 per cent of hammer, the seller receives £110,000 before applicable taxes and other charges.
Now imagine a private intermediary charges the seller a fee of 10 per cent.
To leave that seller with the same £110,000, the intermediary would need to negotiate a private sale of approximately £122,222.
If the private buyer were instead willing to spend the same £128,000 as the auction buyer in our earlier example, the seller would receive £115,200 after the hypothetical 10 per cent fee.
On those assumptions, the private transaction produces more money for the seller.
But that conclusion depends entirely on the private intermediary finding a buyer willing to pay £128,000.
The auction house may be able to produce precisely that demand because of its reputation, marketing and competitive bidding. Without it, the best private offer might be substantially lower.
Lower commission does not necessarily mean a better result.
A similar calculation applies to buyers.
At auction, the buyer can generally determine the maximum hammer bid compatible with a total budget. The public process may also provide comfort through cataloguing, research and established contractual conditions.
Private purchases can offer opportunities for negotiation and tailored terms. They may also permit more extensive discussion of provenance, condition, warranties and payment arrangements.
But buyers should be particularly careful to establish whether an intermediary is acting as an agent, acting as principal or earning compensation from more than one party.
The buyer's own diligence remains essential under either method.
What a price can tell us
The distinction between auction and private sale is often presented as a choice between transparency and discretion.
The reality is more complicated.
Auction houses publicly disclose important information about how objects are offered and what buyers ultimately pay. They also negotiate commercial terms with sellers, underwrite risk and compensate certain participants through arrangements whose full economics are generally unavailable to outside observers.
Private sellers can exercise greater control over price, exposure and negotiation. But the resulting transactions may provide little evidence to anyone beyond the parties involved.
Both methods can be appropriate. Both can produce excellent outcomes. Both can also create situations in which one participant knows substantially more than another.
The relevant measure is not simply the highest headline price.
For a seller, it is the net amount received, the certainty of completion, the risk assumed and the commercial consequences of the chosen route.
For a buyer, it is the total cost, the quality of the information available and the protections governing the acquisition.
For the wider market, the question is different again.
An auction record tells us that a transaction occurred at a reported price, often after a process that others had an opportunity to observe. A private sale may leave us with only the information its participants choose to disclose.
Neither record offers a complete explanation of value.
The £7.1 million Maradona shirt remains an extraordinary public result. What the auction does not tell us is how much Steve Hodge ultimately received, what Sotheby's retained or precisely how any financial commitments surrounding the sale were remunerated.
Those details belong to the less visible market operating around the public one.
The hammer may establish a price.
It does not settle the question of who benefited most from it.